The scale of the artificial intelligence buildout in the United States is creating a new question for the technology industry: will demand for AI services grow quickly enough to justify the enormous investment now going into data centres, power infrastructure, networking equipment and specialised chips?
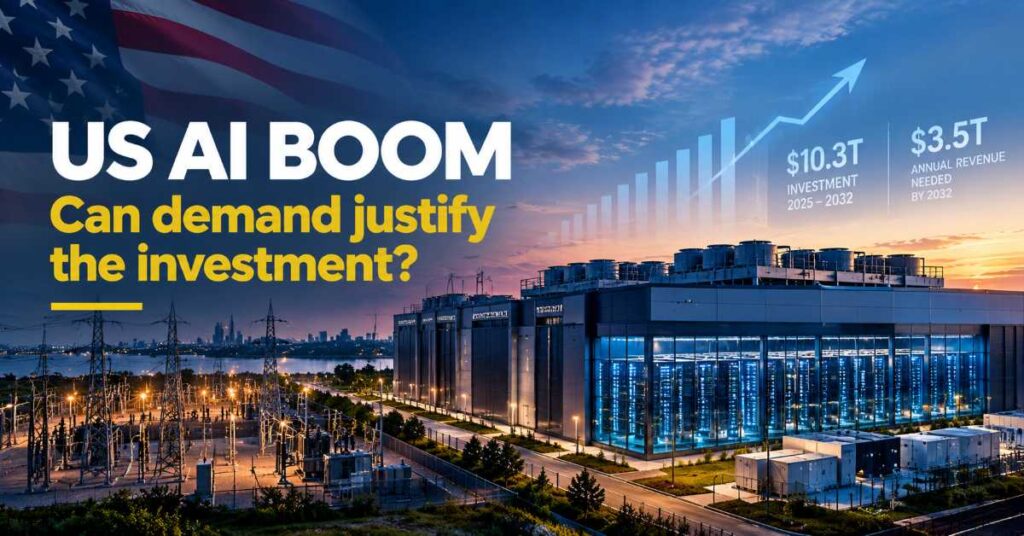
A new paper by Columbia Business School professor Stijn Van Nieuwerburgh estimates that AI-related infrastructure investment could total $10.3tn between 2025 and 2032, equivalent to an average of 3.63% of US gross domestic product each year. The research was presented as part of the Brookings Papers on Economic Activity.
The scale of the projected spending puts the current AI buildout alongside some of the largest infrastructure investment periods in US history. The estimate covers data-centre buildings, power systems, networking infrastructure, specialised chips and other equipment needed to run increasingly demanding AI workloads.
But the investment creates a difficult financial equation. For the infrastructure to generate adequate returns, AI companies will need to develop a much larger pool of paying demand. A Wall Street Journal analysis of Van Nieuwerburgh’s work estimates that AI-related revenue would need to reach about $3.5tn annually by 2032, or roughly 8.8% of projected US GDP, under the assumptions used in the analysis.
That does not mean the US AI industry is currently generating anything close to that amount. Rather, the figure illustrates the level of revenue that could be required to justify the capital being committed today if current assumptions about pricing, cash flow and returns hold.
One of the biggest uncertainties is the price of AI computing. AI models are becoming more capable while the cost of obtaining a given level of capability has been falling rapidly. If computing capacity expands faster than demand, greater competition could eventually put downward pressure on prices and profit margins.
There is also evidence pointing in the opposite direction. Gartner estimates that worldwide spending on AI will reach $2.7tn in 2026, up 49.5% from the previous year, with AI infrastructure representing the largest component of spending. The research firm expects continued investment as companies build capacity for future workloads.
The financial structure behind the buildout is becoming another issue. Van Nieuwerburgh’s research says major technology companies are increasingly using leases, project finance, private credit, securitisation and special-purpose vehicles to fund AI infrastructure. That allows the industry to mobilise more capital, but it can also spread exposure among banks, investors and other financial institutions.
That means the outcome of the AI boom will depend on more than whether consumers continue using chatbots. Businesses will need to find profitable applications for AI, while data-centre operators and technology companies will need enough utilisation and pricing power to generate returns from increasingly expensive infrastructure.
For now, demand remains strong and investment continues. But as the capital committed to the AI buildout reaches unprecedented levels, the industry’s longer-term test is becoming clearer: AI will have to turn technological adoption into enough recurring revenue to support the infrastructure being built ahead of that demand.