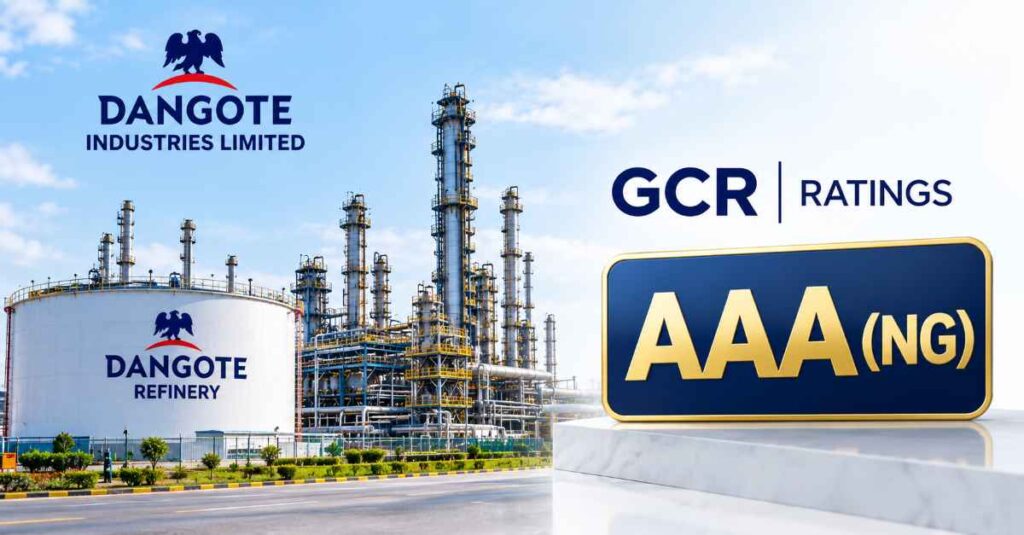
Dangote Industries Limited has been upgraded to the highest national credit rating by GCR Ratings, with the agency citing stronger cash flows from the Dangote Petroleum Refinery, lower leverage and improvements in the group’s capital structure.
GCR upgraded Dangote Industries’ long-term issuer rating to AAA(NG) from A+(NG), while its short-term rating moved to A1+(NG) from A1(NG). The ratings, announced on September 23, carry a stable outlook.
The rating agency also upgraded the long-term ratings on Dangote Industries Funding Plc’s Series 1 Tranche A and Tranche B bonds and Series 2 bonds to AAA(NG) from A+(NG).
GCR attributed the upgrade to stronger operating performance across the group, particularly the ramp-up of the Dangote refinery, which the agency said has improved cash generation. Debt repayment and refinancing on more favourable terms have also strengthened the group’s leverage position.
The improvement represents a significant reversal from the rating action taken by GCR in October 2025, when Dangote Industries was downgraded to A+(NG)/A1(NG). At that time, the agency pointed to higher short-term debt following the refinery’s ramp-up and the effect of exchange-rate movements on a loan book with substantial foreign-currency exposure.
The group’s financial position has since improved. GCR’s latest assessment shows gross debt falling from a peak of about ₦15.2 trillion in 2024 to ₦10.2 trillion as of June 2026, while cash holdings exceeded ₦9.3 trillion. Its EBITDA margin also increased from 13.9 per cent in 2025 to 23.9 per cent in the first half of 2026.
The stronger balance sheet comes as the refinery moves into a more mature operating phase. Higher refinery throughput has increased the contribution of the oil and gas business to the group’s earnings, helping to improve its ability to generate cash and service its obligations.
GCR, however, does not expect Dangote Industries’ debt to continue falling indefinitely. The agency forecasts gross debt could rise to about ₦11.5 trillion in 2026 and ₦14.7 trillion thereafter as the group finances planned expansion, including an additional refining line in Nigeria and a new refinery project in Kenya.
For investors and businesses that follow Nigeria’s corporate debt market, the upgrade is significant because it changes the credit assessment attached to Dangote Industries and its rated bonds. It also shows how the financial profile of the group is changing as the refinery moves from a major investment project into an increasingly important source of operating cash flow.
The next test will be whether Dangote Industries can maintain the stronger leverage and liquidity position while funding its planned expansion. GCR has retained a stable outlook, indicating that the agency expects the factors supporting the current rating to remain broadly intact.